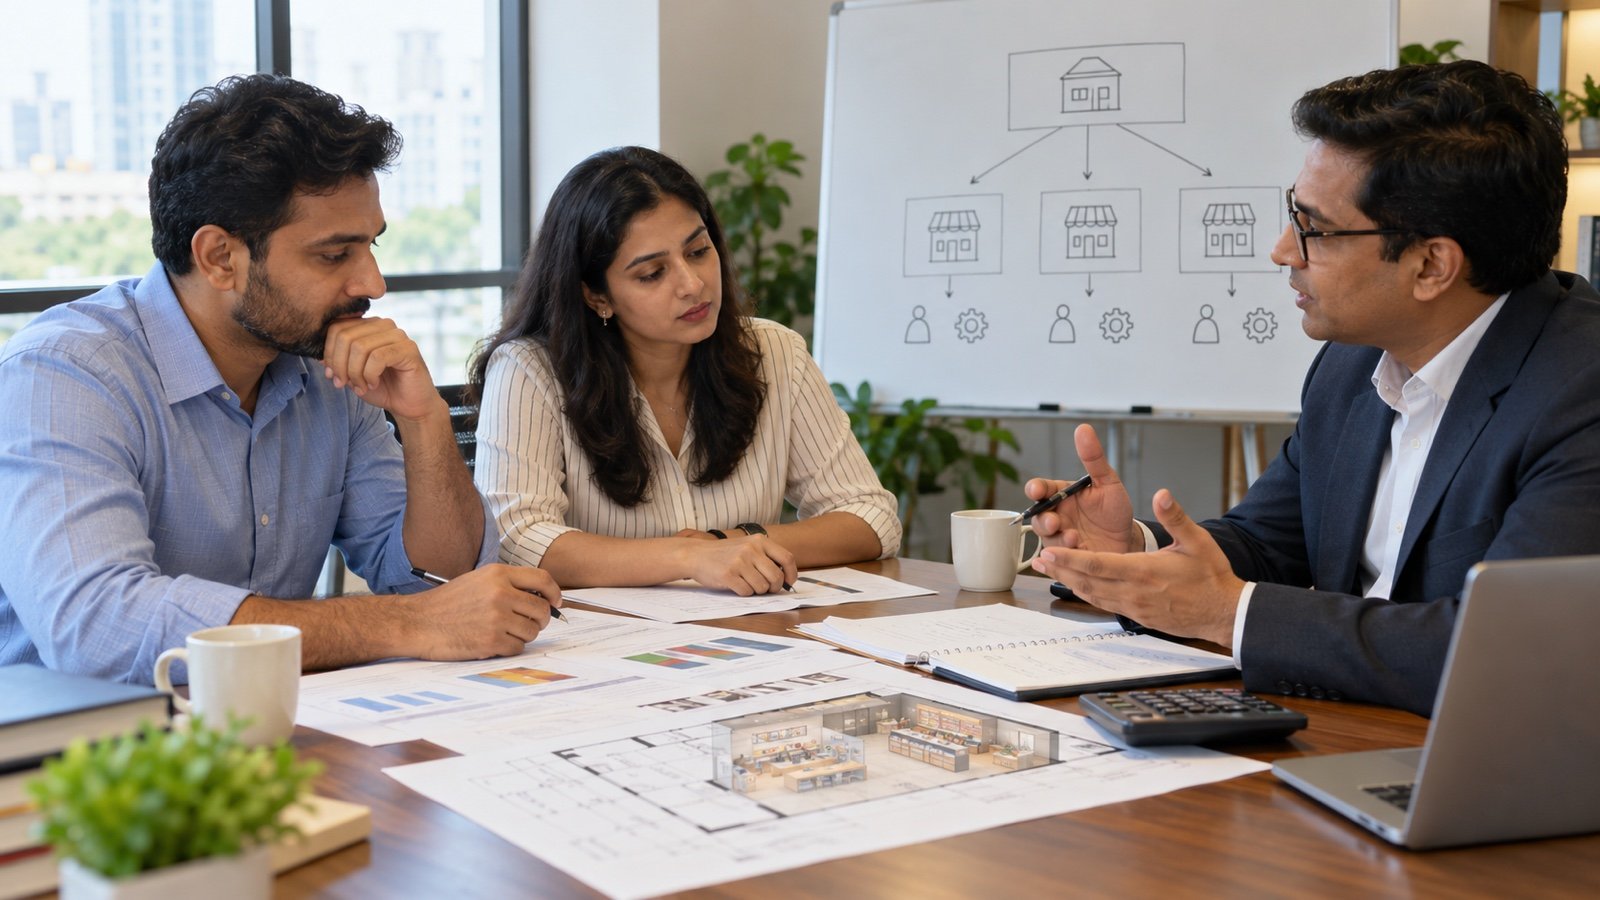
FOFO, FOCO and COCO are widely used shorthand in Indian franchise conversations, but the labels can create false confidence. Two offers carrying the same label may allocate rent, staff, inventory, licences, working capital, losses and exit obligations very differently. The signed documents and actual operating system matter more than the acronym.
The simplest way to compare the models is to ask two questions: who funds and owns the outlet assets, and who controls daily operations? This guide explains the common structures, their trade-offs and the due-diligence questions both franchise investors and growing brands should answer.
1. FOFO: franchise-owned, franchise-operated
In a FOFO structure, the franchisee generally funds the outlet and manages daily operations under the brand’s system. The franchisor typically provides the brand, standards, training, supply rules and ongoing support. The franchisee usually carries significant execution risk, so local management ability matters as much as capital.
- Potential fit: an owner who wants operating control and can lead people locally.
- Main advantage: strong local ownership and faster market adaptation within brand rules.
- Main risk: inconsistent execution when training, audits or manager capability are weak.
- Verify: territory, approved vendors, pricing authority, staffing, reporting and royalty calculation.
2. FOCO: franchise-owned, company-operated
In a FOCO structure, the franchisee generally contributes the outlet investment while the brand or its operating entity manages day-to-day operations. This can suit investors who do not want to run the unit personally, but it does not automatically create passive or guaranteed income. The agreement must explain operational control, account access, costs, revenue share and what happens when the unit underperforms.
3. COCO: company-owned, company-operated
A COCO outlet is funded and run by the company. It may be used to enter a strategic market, test a format, train teams or maintain direct control. For an external investor it is normally not a franchise investment opportunity, but it provides useful evidence: visit company-operated units to understand the brand’s real standards, economics and operating discipline.
4. COFO and hybrid arrangements
COFO usually means company-owned, franchise-operated: the company controls the asset or capital while a partner operates the unit. Other hybrid arrangements may split inventory, fit-out, staffing or revenue in unique ways. Never infer the economics from the label; map every obligation and cash flow from the actual documents.
5. Compare ownership, operations and economic exposure separately
Create a responsibility matrix before comparing returns. List who pays the franchise fee, deposit, fit-out, rent, utilities, licences, technology, recruitment, salaries, inventory, local marketing, insurance, repairs and working capital. Then identify who absorbs shrinkage, refunds, discounts, bad debt and operating losses.
A revenue-share percentage is not the same as profit. Calculate cash flow after every recurring cost, tax, reserve and replacement obligation. Review projections with qualified legal, accounting and financial professionals.
6. Treat “fixed return” and “guaranteed income” carefully
Ask which legal entity promises the payment, how it earns the cash, whether the obligation is conditional, what security exists and what remedy applies after delay or default. Compare the promise with audited capacity and unit-level economics. A strong brochure cannot substitute for a solvent counterparty and enforceable agreement.
7. Define who controls the people and customer experience
Clarify who recruits, trains, schedules, appraises and removes employees; who is legally responsible for employment obligations; and who handles complaints. In a company-operated model, investors should still understand escalation and reporting. In a franchise-operated model, the brand should test whether local leadership can protect standards without constant intervention.
8. Demand transparent unit economics and data access
Review actual mature and recently opened units—not only the best-performing example. Ask for sales, gross margin, occupancy, payroll, wastage, local marketing, royalty, break-even time and working-capital movement. Confirm what dashboard, bank, billing and inventory data each party can access and how often reconciliation occurs.
9. Test brand support beyond the opening ceremony
Meet existing and former partners. Ask what happened after launch, during a weak month, when staff left or when supply failed. Inspect training, field visits, marketing support, technology, product development and complaint resolution. A scalable system should help an ordinary trained team deliver the promise repeatedly.
10. Read the agreement for control, change and exit
Review territory protection, term, renewal, transfer, audit rights, price changes, vendor restrictions, data ownership, intellectual property, non-compete clauses, termination, cure periods and dispute resolution. State who owns furniture, equipment, customer records, deposits and unsold inventory at exit, and who pays restoration or employee costs.
11. Match the model to your role and capability
FOFO may suit an engaged local operator with management capability. FOCO may suit an investor comfortable with lower daily control and strong dependence on the operator’s governance. COCO suits a brand willing to deploy its own capital and operating team. COFO may suit a capable operator who does not own the site or core assets. None is universally superior; the fit depends on control, capital, capability and risk tolerance.
12. Use this decision checklist before paying
Complete the commercial, operational and legal investigation before signing or transferring money.
- Identify every investing, operating, licensing and payment entity.
- Model base, downside and delayed-opening cash flows.
- Verify rent, site approvals, licences and working-capital responsibility.
- Speak independently with several current and former partners.
- Visit both company-operated and partner-operated outlets where possible.
- Confirm bank, POS, inventory and audit access in writing.
- Understand performance obligations, default remedies and exit costs.
- Have the complete agreement reviewed by qualified professionals.
A practical rule for both brands and investors
Do not sell or buy an acronym. Build a responsibility map, a conservative unit P&L and a realistic operating calendar. If either party cannot explain who acts, who pays, who decides and what happens when performance misses plan, the opportunity is not ready for commitment.
Key takeaways
Put the framework into action
- FOFO, FOCO and COCO describe ownership and operation broadly; the agreement defines the real obligations.
- Compare total cash exposure, control, data access and downside—not headline return alone.
- Verify the system through actual units and partners before investing or expanding.
Research sources
Sources & further reading
This article provides general business education, not legal, tax or financial advice. Adapt the framework to your market and consult qualified professionals where required.